Compound Interest Formula: How to Calculate It With Examples
Compound interest can help savings grow over time because interest is earned on the original deposit and on interest added in earlier periods. The compound interest formula shows how much money may accumulate when you know the starting amount, annual interest rate, compounding frequency and time. For someone saving in Singapore dollars, even a simple example using S$1,000 can show how the numbers change over several years. Below, you’ll find the formula, worked calculations, monthly compounding, Excel examples and a few Singapore-specific points to check before making savings decisions.
TL;DR — Compound Interest Formula at a Glance
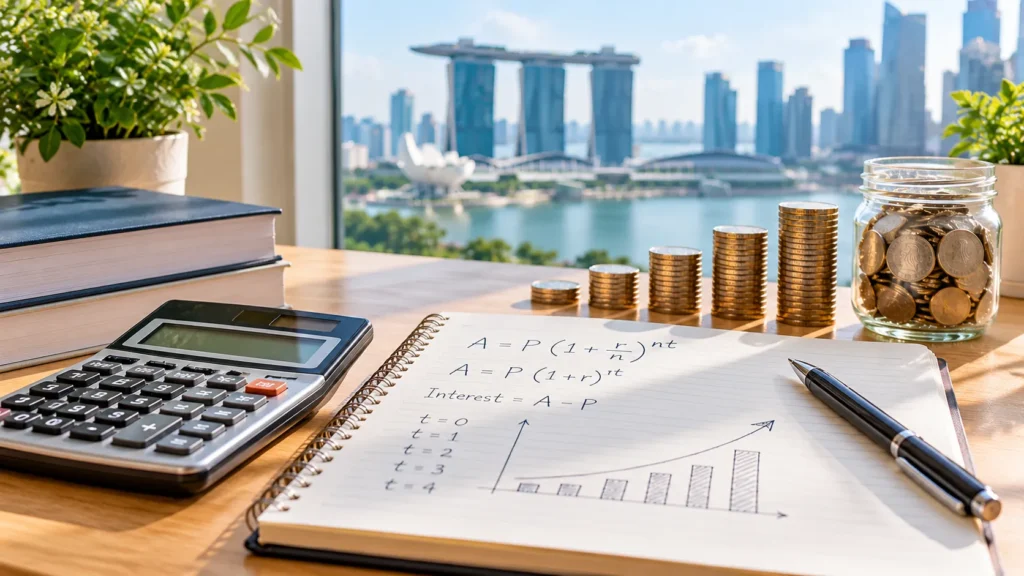
The standard compound interest formula is:
\[ A=P\left(1+\frac{r}{n}\right)^{nt} \]
- A: Final balance, including principal and interest
- P: Starting principal or deposit
- r: Annual interest rate as a decimal
- n: Number of compounding periods per year
- t: Time in years
To calculate interest earned, subtract the starting principal from the final balance: \(CI=A-P\).
What Is the Compound Interest Formula?
The compound interest formula calculates the future value of money when interest is added to the balance at regular intervals. After each compounding period, the next interest calculation uses the updated balance rather than just the original deposit. That’s the main difference between compound and simple interest. For example, if you deposit S$1,000 into an account paying a hypothetical 4% annual rate, the first year’s interest is S$40. If that interest stays in the account, the second year’s interest is calculated on S$1,040 — not just S$1,000.
Understanding Each Variable in the Formula
- Principal (P): The amount you deposit at the start. Here, it’s S$1,000.
- Annual interest rate (r): The yearly rate written as a decimal. Convert 4% to 0.04 before using it in the formula.
- Compounding periods (n): How often interest is added each year. Annual compounding uses 1; monthly compounding uses 12.
- Time (t): How long the money remains invested or deposited, measured in years. The result, \(A\), is the accumulated balance or future value. It includes both your original money and the interest added over time.
Formula for Compound Interest Earned
Use this simple equation to find the interest portion:
\[ CI=A-P \]
If your final balance is S$1,216.65 and you started with S$1,000, the interest earned is S$216.65. The final balance and the interest earned are different figures, so don’t mix them up when comparing savings projections.
How to Calculate Compound Interest Step by Step
Let’s work through a compound interest calculation in Singapore dollars. Suppose you deposit S$1,000 at a hypothetical 4% annual interest rate for five years, with interest compounded once a year. This rate is only an example, not a claim about a current Singapore bank account. Step 1: Write down the values.
- Principal: \(P=1000\)
- Annual rate: \(r=0.04\)
- Compounding periods per year: \(n=1\)
- Time: \(t=5\) years Step 2: Substitute them into the formula.
\[ A=1000\left(1+\frac{0.04}{1}\right)^{1\times5} \]
Step 3: Calculate the growth factor.
\[ A=1000(1.04)^5 \]
Step 4: Work out the final amount.
\[ A=1000\times1.2166529\approx S\$1,216.65 \]
Your projected balance after five years is S$1,216.65. Subtract the initial S$1,000 and you get S$216.65 in interest earned.
Year-by-Year Compound Interest Calculation
Here’s how the same deposit grows over its first three years if the rate stays at 4% and interest is added annually.
| Year | Starting balance | Interest earned | Ending balance |
|---|---|---|---|
| 1 | S$1,000.00 | S$40.00 | S$1,040.00 |
| 2 | S$1,040.00 | S$41.60 | S$1,081.60 |
| 3 | S$1,081.60 | S$43.26 | S$1,124.86 |
Notice how the yearly interest rises even though the rate stays the same. The balance is growing, so each new calculation starts with a slightly larger amount.
Monthly Compound Interest Formula
Monthly compounding means interest is added to the balance 12 times a year. To calculate it, divide the annual interest rate by 12 and multiply the number of years by 12 to get the total periods.
\[ A=P\left(1+\frac{r}{12}\right)^{12t} \]
For example, suppose S$1,000 earns a hypothetical 5% nominal annual rate for three years, compounded monthly:
\[ A=1000\left(1+\frac{0.05}{12}\right)^{36} \]
The final balance is approximately S$1,161.47, including about S$161.47 in interest. Actual returns depend on the account’s terms, rate and fees.
How to Calculate Compound Interest Monthly
The monthly formula follows the same principle as the annual formula. The difference is the number of compounding periods: monthly compounding uses 12 periods per year, while annual compounding uses one. For a fair comparison, keep the principal, annual rate and duration the same.
Compound Interest With Monthly Deposits
Adding money each month is a separate calculation from compounding a single deposit. For fixed deposits made at the end of each month, the future value of those contributions can be calculated with an annuity formula:
\[ FV=PMT\left(\frac{(1+i)^m-1}{i}\right) \]
Here, \(PMT\) is the monthly deposit, \(i\) is the monthly interest rate and \(m\) is the total number of monthly deposits. If deposits are made at the beginning of each month, the result is multiplied by \((1+i)\). When you also have an initial lump sum, calculate its future value separately and add the two amounts.
Compound Interest by Compounding Frequency
The compounding frequency tells you how often interest is added to the balance. With the same nominal annual rate and all other inputs held constant, more frequent compounding generally produces a slightly higher balance.
| Compounding frequency | Periods per year |
|---|---|
| Annually | 1 |
| Semiannually | 2 |
| Quarterly | 4 |
| Monthly | 12 |
| Daily | 365 |
Here’s a comparison using S$1,000, a hypothetical 5% nominal annual rate and three years, with no additional deposits.
| Frequency | Approximate final balance |
|---|---|
| Annually | S$1,157.63 |
| Semiannually | S$1,159.69 |
| Quarterly | S$1,160.75 |
| Monthly | S$1,161.47 |
| Daily | S$1,161.79 |
These are formula-based estimates, rounded to the nearest cent. The difference between monthly and daily compounding is small in this example. Actual savings products may calculate interest differently, and fees or rate changes can affect the final amount.
Simple Interest vs Compound Interest
Simple interest is calculated only on the original principal. Compound interest is calculated on the principal plus any interest already added to the balance. Over time, that difference can grow.
For example, consider S$1,000 earning a hypothetical 5% annually for three years, with no extra deposits.
| Method | Calculation | Final balance |
|---|---|---|
| Simple interest | S$1,000 + (S$1,000 × 5% × 3) | S$1,150.00 |
| Compound interest | S$1,000 × (1.05)³ | S$1,157.63 |
The compound interest balance is S$7.63 higher in this example. The gap tends to widen over longer periods because interest can earn further interest. The actual difference depends on the rate, time and compounding terms.
How to Calculate Compound Interest in Excel
Excel and Google Sheets can calculate a future balance in one formula. For S$1,000 at a hypothetical 5% annual rate, compounded monthly for three years, enter:
=1000*(1+5%/12)^(12*3)
The result is approximately S$1,161.47. To calculate the interest earned separately, subtract the starting principal:
=1000*(1+5%/12)^(12*3)-1000
For a spreadsheet you can reuse, place the principal, annual rate, years and compounding periods in separate cells, then reference those cells in the formula. Change the inputs whenever you want to test a different savings scenario.
Compound Interest in Singapore
For Singapore savers, compound interest calculations can help estimate how a deposit might grow in SGD over several years. But a formula gives a projection, not a promise of what a bank will pay. Check the account’s stated interest rate, qualifying conditions, fees and how interest is credited before relying on an estimate. CPF savings have their own rules and applicable interest rates. For accurate details about CPF interest and how it applies to different CPF accounts, consult the official CPF Board website. A standard compound interest formula is useful for learning the maths, but it may not capture every CPF-specific rule.
Frequently Asked Questions About Compound Interest
What is the formula for compound interest?
The standard compound interest formula is \(A=P(1+r/n)^{nt}\). Here, \(P\) is the initial principal, \(r\) is the annual rate as a decimal, \(n\) is the number of compounding periods per year and \(t\) is the time in years. Subtract the principal from the final amount to find the interest earned.
How do you calculate compound interest monthly?
Use \(A=P(1+r/12)^{12t}\) for a single starting deposit when the nominal annual rate is compounded monthly. Divide the annual rate by 12 and multiply the number of years by 12. Regular monthly deposits require an additional calculation.
What is the difference between the final amount and interest earned?
The final amount includes the original principal and all accumulated interest. Interest earned is only the growth above your starting deposit. For example, a S$1,000 deposit growing to S$1,200 has earned S$200 in interest.
Can I calculate compound interest in Excel?
Yes. Enter =1000*(1+5%/12)^(12*3) to estimate the final value of S$1,000 at a hypothetical 5% annual rate with monthly compounding over three years. The result is approximately S$1,161.47.
Is compound interest used for CPF savings in Singapore?
CPF savings earn interest under CPF-specific rules, which vary by account and applicable policy. The general compound interest formula can illustrate growth, but it may not represent every CPF calculation or interest crediting rule. Check the latest details directly with the CPF Board.
Conclusion — Compound Interest Formula
The compound interest formula estimates a future balance using the starting principal, annual interest rate, compounding frequency and time. It also helps separate the final amount from the interest earned. For Singapore savers, working with SGD examples makes the calculation easier to follow. Enter your own figures into the formula or a compound interest calculator Singapore readers can use, then compare the estimate with the actual account terms before making financial plans.